UP CM YUVA Scheme: Interest-Free Loan for Youth
Overview
UP's CM YUVA scheme gives youth aged 21-40 collateral-free loans up to ₹5 lakh with interest subsidy. Check eligibility, documents and how to apply.
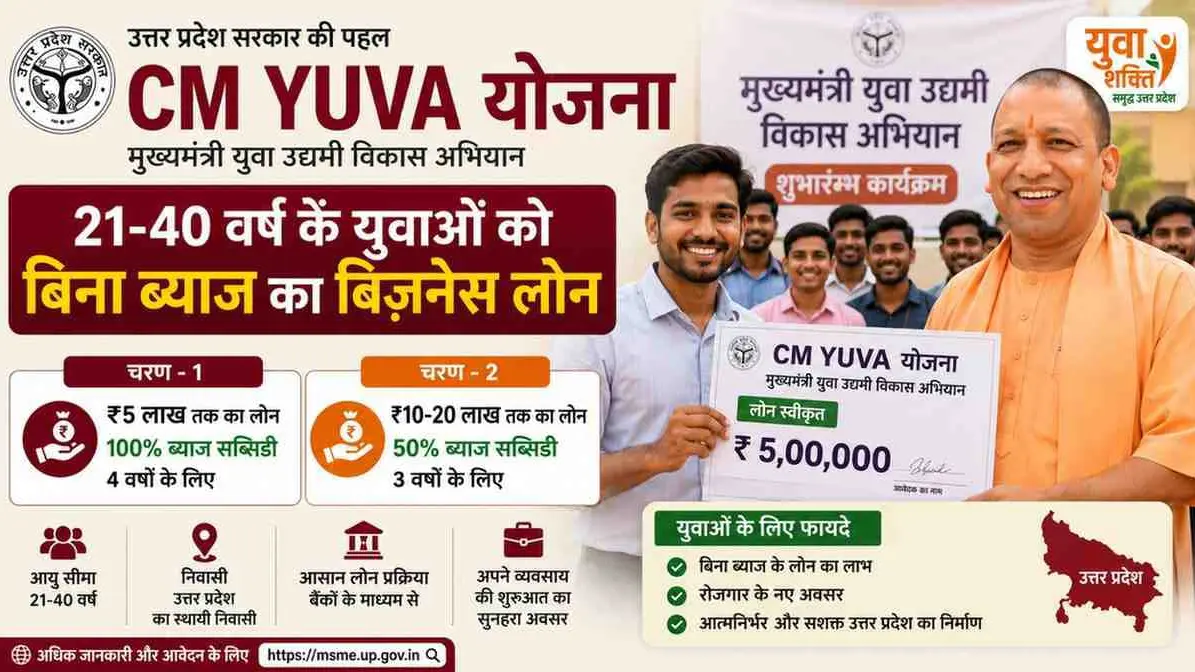

Uttar Pradesh's youth now have a real shot at starting their own business without worrying about collateral or high interest rates. The state government's Mukhyamantri Yuva Udyami Vikas Abhiyan, better known as the CM YUVA scheme, is designed to help first-time entrepreneurs in the 21 to 40 age group set up small enterprises with financial backing from the government.
The scheme isn't new, but it continues to be one of the most talked-about self-employment programmes in the state, largely because it removes two of the biggest hurdles young applicants usually face when applying for a business loan: the need for a guarantor and the burden of interest payments in the early years.
What the CM YUVA Scheme Offers
The scheme is structured in two phases, and the benefits differ depending on which one an applicant qualifies for.
Phase 1 is meant for smaller, first-time ventures. Eligible applicants can get loans of up to ₹5 lakh, and the state government covers 100% of the interest for four years. In effect, this makes the loan interest-free for that period, as long as repayments stay on track.
Phase 2 is aimed at applicants looking to scale up or start slightly larger units. Under this phase, loans range from ₹10 lakh to ₹20 lakh, with a 50% interest subsidy for three years. This phase typically requires more documentation and a more detailed project report, since the loan amounts are higher.
Both phases are routed through banks and financial institutions empanelled with the state government, and eligible beneficiaries are not required to pledge collateral or bring in a guarantor, which is unusual for loans of this size.
Who Can Apply
Based on the official scheme guidelines, the core eligibility criteria are:
- Applicant must be between 21 and 40 years of age
- Must be a permanent resident of Uttar Pradesh
- Should have passed at least Class 8; those with higher qualifications, especially Class 12 and above, are often given preference during selection
- Should not have any history of loan default with a bank or financial institution
- Should not already be availing benefits under a similar state or central self-employment scheme
The scheme is open to a wide range of business ideas, from manufacturing and services to trading units, though certain categories fall under a negative list and are not eligible for funding. Applicants are advised to check the current list on the official portal before finalising their business plan.
Documents You Will Need
While exact requirements can vary slightly by bank, applicants are generally expected to keep the following ready:
- Aadhaar card and other identity proof
- Domicile or residence proof for Uttar Pradesh
- Educational qualification certificates
- Passport-size photographs
- Bank account details
- A basic project report or business plan outlining the proposed enterprise
- Udyam Registration Certificate, once the unit is set up
How to Apply
Applications for the CM YUVA scheme are accepted through the official Uttar Pradesh government portal, and applicants can also approach their local District Industries Centre (DIC) for guidance. The process typically involves:
Registering on the scheme's online portal with basic personal details
Filling in the business plan and loan requirement
Uploading the required documents
Submission for verification at the district level
Forwarding of approved applications to empanelled banks for loan sanction and disbursement
Once a bank sanctions the loan, disbursement usually happens directly to the applicant's account, followed by monitoring of interest subsidy and margin money claims by the concerned bank branch.
Why This Matters for UP's Youth
For many young people in smaller towns and rural parts of Uttar Pradesh, the biggest barrier to starting a business has never been the idea — it's been access to affordable capital without a guarantor. The CM YUVA scheme directly addresses that gap. A four-year interest-free window on a ₹5 lakh loan can make a real difference for someone setting up a small manufacturing unit, a retail shop, or a service-based business, since it gives the enterprise time to stabilise before EMI pressure builds in full.
Applicants planning their loan can use an online EMI calculator to estimate repayment schedules once the interest subsidy period ends, which helps in planning cash flow for the business more realistically.
Things to Keep in Mind
The government has been pushing banks to speed up disbursements under the scheme as part of its broader target of setting up new micro-enterprises each year. That said, processing timelines can still vary by district and by bank, so applicants should stay in touch with their DIC or bank branch after submission rather than assuming automatic approval.
It's also worth noting that beneficiaries who default in Phase 1 become ineligible for Phase 2 financing, so timely repayment matters not just for individual credit history but for future scheme benefits as well.
Conclusion
The CM YUVA scheme remains one of the more practical routes for young entrepreneurs in Uttar Pradesh to access collateral-free, subsidised credit. Whether it's a ₹5 lakh interest-free loan under Phase 1 or a larger Phase 2 loan for expansion, the scheme is built to ease the financial starting point for first-generation business owners. Anyone eligible and serious about starting a venture would do well to prepare their documents and project report early, since a well-prepared application tends to move faster through the verification process.
For More Information -
https://msme1connect.up.gov.in/scheme-list/mukhyamantri-yuva-swarojgar-yojana
> Disclaimer: The content provided on LabhGrow is for educational and informational purposes only. We are not a SEBI-registered investment advisor. Please consult a qualified financial advisor before making any investment or financial decisions. LabhGrow is not responsible for any loss or damage arising from the use of this information.

Head of Content & Lead Writer
Senior financial & news writer specializing in Indian government schemes, market rates, and banking policies.
lakshyabhardwaj.hoc@labhgrow.in
Senior Research Analyst (Fact-Checker)
Dedicated researcher and data verifier ensuring 100% authenticity and fact-checking from primary government and financial feeds.
harshitsharma.sra@labhgrow.in